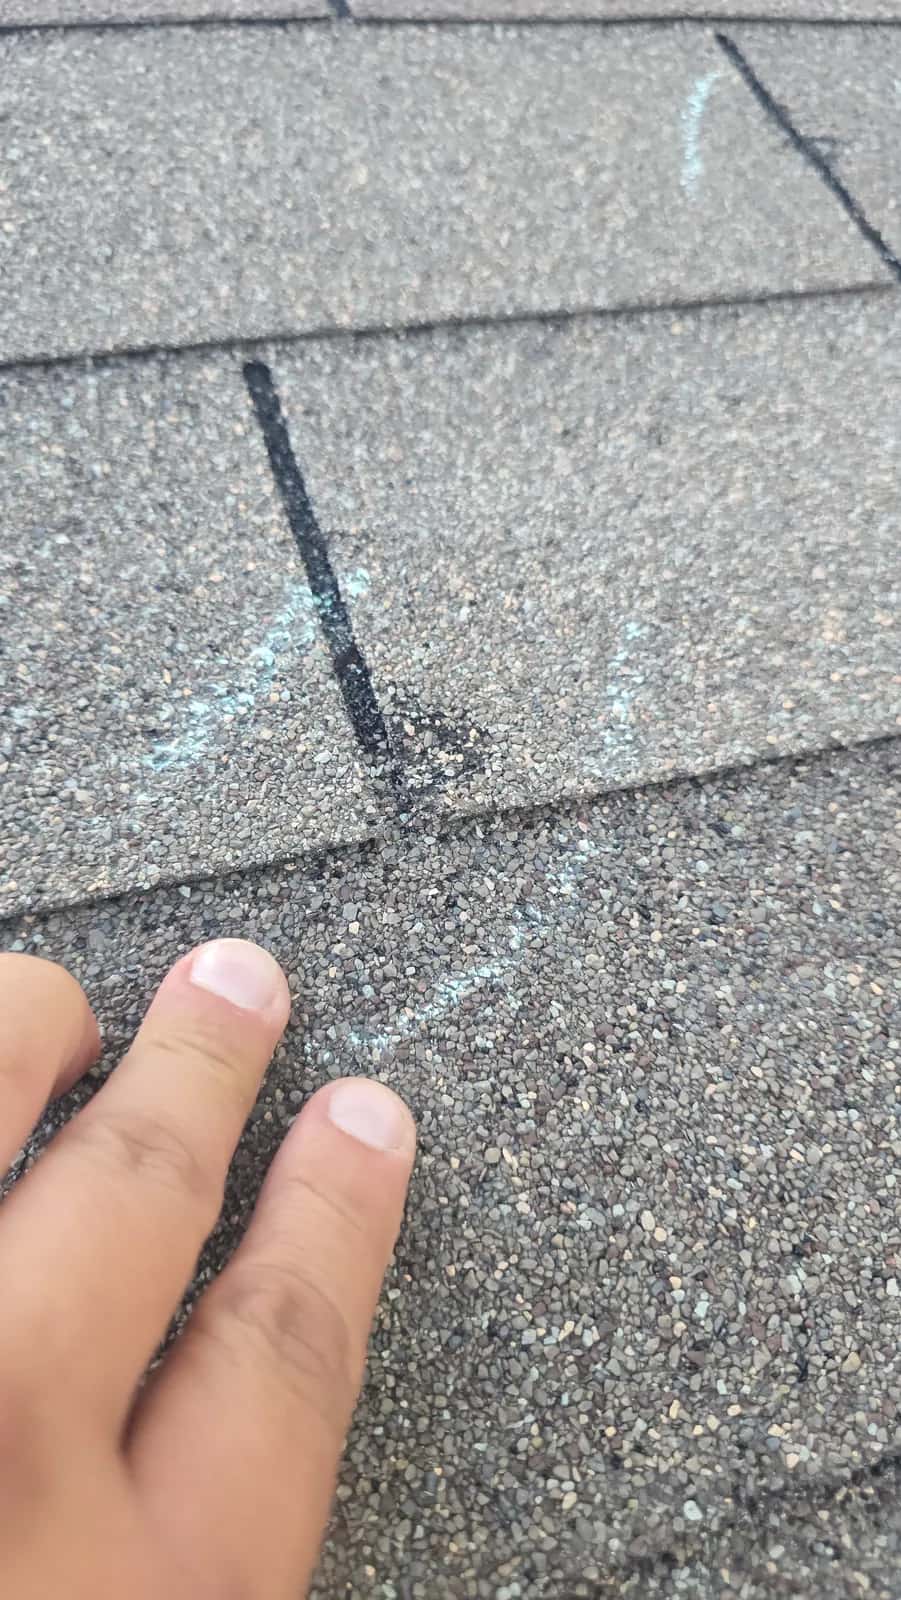
Close-up of a hand pointing to a chalk-circled hail impact on a gray asphalt shingle

Insurance Claims

Hail Damage Insurance Claim Help in San Antonio, TX

Hail damage insurance claim help in San Antonio begins with a free look at your roof and runs until the carrier sends the last check. Former insurance adjusters work on our in-house staff, bringing 30+ years of insurance claim experience. We document the hail, meet your adjuster up top, check the scope, file supplements and chase the depreciation your policy holds back. Your part is the deductible. The paperwork's ours.

  • Former insurance adjusters on staff
  • We meet the adjuster on your roof
  • Supplements filed, not forgotten
  • Recoverable depreciation, recovered

Preferred
brands

Owens CorningGAF

Google5.016 reviews

  • Veteran Owned
  • Registered and Insured
  • San Antonio and Austin

What is included with hail damage insurance claims

  • Former insurance adjusters on staff

    Some of our people used to write estimates for carriers. They know how a hail roof gets scoped, and they know which lines usually go missing.
  • We meet the adjuster on your roof

    You won't face the adjuster by yourself. We chalk the hits, mark the test squares and take the adjuster across the roof one slope at a time.
  • Supplements filed, not forgotten

    Decking, drip edge, starter strip, code items. When the first scope skips something, we send a supplement with the photos to back it.
  • Recoverable depreciation, recovered

    The sixth step in our process is the final inspection and the depreciation release. Most homeowners never ask for that check. We always do.
  • Deductible handled by the book

    Under Texas HB 2102, no contractor can waive or absorb your deductible. We won't. If somebody offers to, show them the door.

How a hail damage insurance claim works in Texas

Plenty of roofs that look fine from the driveway fail the test square. We saw it after April 12, 2016, when hail up to 4.5 inches fell on Helotes and northwest San Antonio in what was then the costliest hail event in Texas history. We saw it again on September 24, 2023, when 4-inch stones hit Round Rock and north Austin and the National Weather Service called it the most costly storm damage ever to hit the Austin region. That cell ran from Georgetown through Round Rock into Austin, dropping quarter-size hail as far out as Pflugerville. Texas has led the country in major hail events for years, and Central Texas gets more than its share, so a hail damage insurance claim is something a lot of families here end up filing.

Start with your deductible. Most Texas homeowner policies have a separate wind and hail deductible, written as a percentage of dwelling coverage (often 1 or 2 percent) instead of a flat dollar amount. A 2 percent deductible costs you twice what a 1 percent one does on the same dwelling limit. Find that line on your declarations page before you file. Then there's how the money arrives. On a replacement-cost policy, the carrier's first check covers actual cash value, meaning the roof's depreciated worth. The rest, called recoverable depreciation, waits until the work's done and the invoice goes in. That money belongs to you, and most homeowners never collect it.

Two more rules. Your policy gives you a window to report hail damage, often a year or two from the storm, so look it up and don't sit on a roof you're worried about. And since 2019, Texas HB 2102 has made it illegal for a contractor to waive, absorb or rebate your deductible, and your carrier can ask for proof you paid. If a roofer says they'll "take care of" the deductible, they're putting your claim at risk.

We've done 2,800+ projects, and the inspection before you call the carrier is what decides most claims. Get a hail damage roof inspection that covers every slope. Then file.
Our six-step hail claim process

Every hail claim we take follows the same six steps, in the same order, and the order isn't arbitrary. The build side lives on our full process page. Below is the claim side.

  1. Free estimate. It opens with a free roof evaluation. We walk each slope, chalk the hits, photograph the soft metals and write up a scope you can actually file with. Without documentation, there's no claim.
  2. Meet the adjuster. We're already on the roof when the carrier's adjuster pulls up. Our in-house former adjusters talk the same language, point at the same test squares and keep everyone focused on what the hail did.
  3. The audit process. The carrier's scope goes side by side with ours, one line at a time. Decking, drip edge, starter, ridge, pipe boots, gutters. Anything left out gets flagged.
  4. Supplemental report. We send the missing items back to the carrier as a supplement, with photos and measurements. Claims grow at this step. It's also where roofers who don't know claims tend to quit.
  5. Begin building. When the carrier signs off on the scope, we order Owens Corning or GAF shingles and get a crew up there. We've got 8 full crew teams, so you're not stuck in line behind somebody else's job.
  6. Inspection and recoverable depreciation. We inspect the finished roof, send the carrier the completion paperwork and ask for the depreciation check. That's money your policy owed you all along.

All six steps go through our insurance claims team in San Antonio. For Travis and Williamson County claims, the Austin line handles things through our Austin service area.

Why San Antonio homeowners hand their hail claim to Texas-RRR

Installing a roof is one skill. Reading a carrier's estimate is another, and very few roofers have ever worked the adjuster's side of it. Our in-house staff includes former insurance adjusters. Charlie Carreon, who owns the company, has three decades in roofing, and our crews have been side by side with us for over 20. We're veteran owned, registered and insured, and estimates are always free.

Customers say it better. Yvette D. wrote on Google: "they dealt with the insurance company so I didn't have to. They're knowledge and experience helped me get the best settlement." Cory L.'s metal roof quote got turned down at first: "We got a quote for a metal roof and they were rejected by our insurance ... their team had us approved and repaired".

Now the caveat. Nobody here will promise you a full replacement before the roof's been walked, and we won't file a claim on a roof that's just worn out. Hail bruises, wind creases and dented vents are what make a claim. Twenty summers of Texas sun do not. When it's wear and not damage, we'll tell you, and quote a roof replacement on its own.

Call (210) 802-6906 with your address. We'll set up the free evaluation, and if the hail damage is there, we'll carry the claim from the first photo to the final check.

Hail Damage Insurance Claims questions, answered

Free estimates, Mon to Sat, 7 AM to 6 PM

Start your hail damage insurance claim with a free roof evaluation

Call (210) 802-6906 or send the address over. We'll document the hail, meet your adjuster, and keep at the claim until the depreciation check clears.

Call NowFree estimate