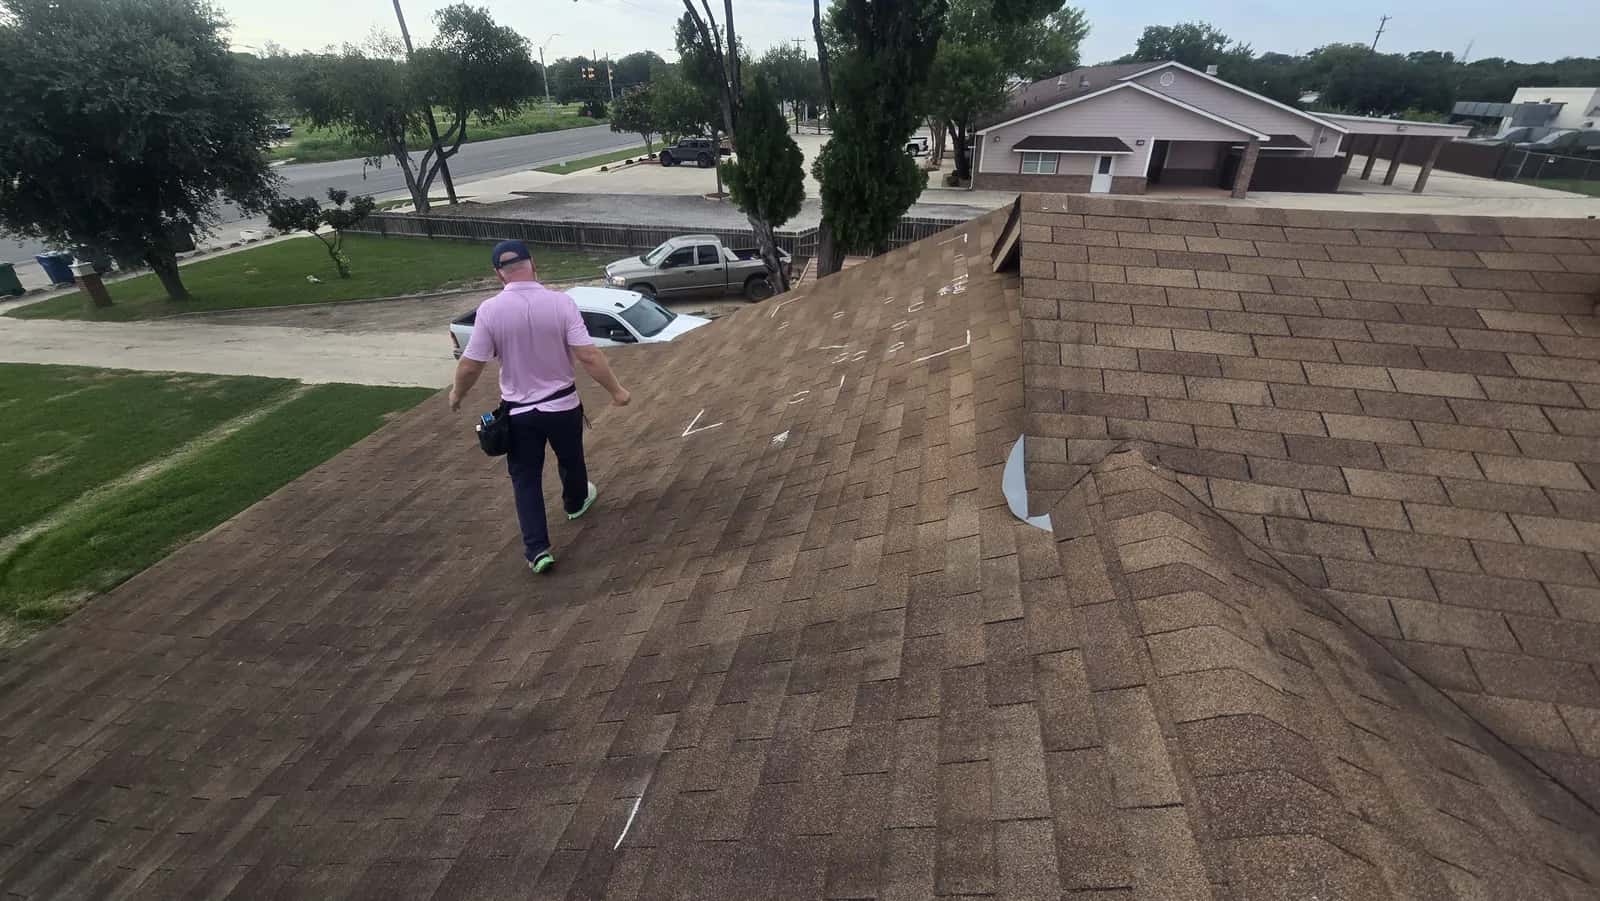
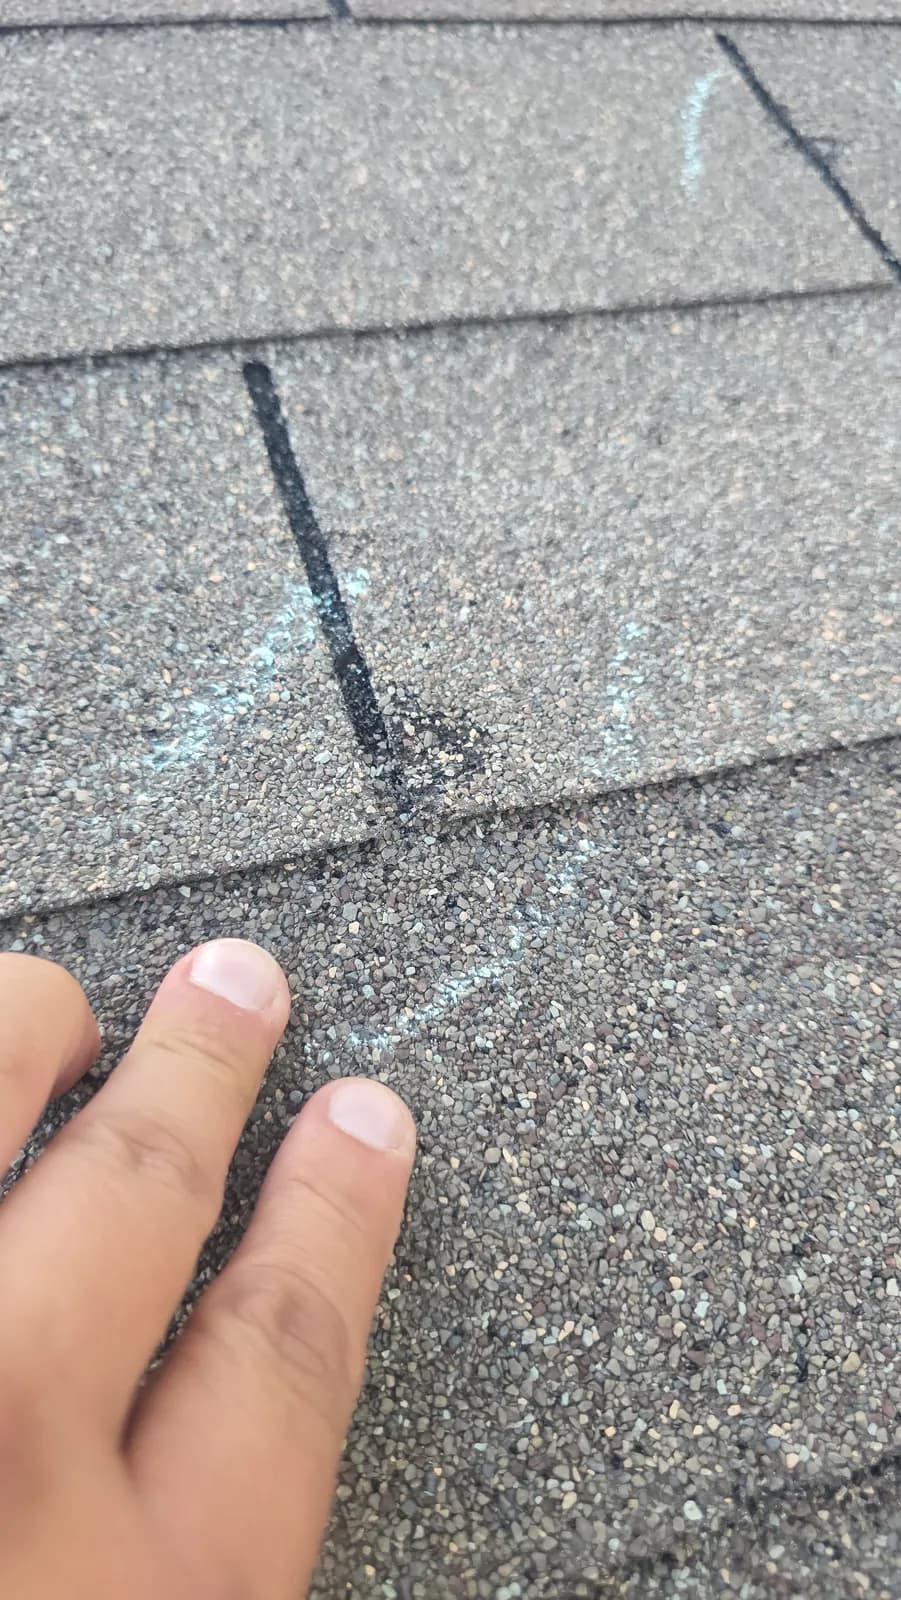
Inspector walking a brown shingle roof marked with chalk during a hail damage inspection, street and trees beyond

Insurance Claims

Roof Insurance Claim Help in San Antonio, TX

Roof insurance claim help in San Antonio, TX, from people who used to sit on the insurer's side of the table. Our in-house staff includes former insurance adjusters, and the team brings 30+ years of insurance claim experience to every hail and wind claim. We inspect free. We meet your adjuster on the roof, audit the scope, file the supplement, build the roof and collect your recoverable depreciation. You pay your deductible, and that's it.

  • Former adjusters on staff
  • 30+ years of claim experience
  • We meet the adjuster for you
  • Supplements and depreciation handled

Preferred
brands

Owens CorningGAF

Google5.016 reviews

  • Veteran Owned
  • Registered and Insured
  • San Antonio and Austin

What sets our insurance claims apart

  • Former adjusters on staff

    Some of our in-house people used to write claim scopes for insurers. They know what a carrier will approve, what it'll fight, and how to document the gap.
  • 30+ years of claim experience

    Our team brings 30+ years of insurance claim experience and 2,800+ projects. Hail, wind, fallen trees, even hurricane remnants.
  • We meet the adjuster for you

    Nobody should be stuck alone on a ladder next to a stranger with a clipboard. We walk the roof with the insurer's adjuster and show them every hit, crease and soft spot.
  • Supplements and depreciation handled

    First scopes nearly always miss something. We write the supplemental report, chase the approval, then file the final invoice that releases your recoverable depreciation.
  • Honest about deductibles

    Waiving a deductible is a crime under Texas law (HB 2102, 2019). We won't ever offer it, and if a roofer does, you should walk away.
  • Both metros, one process

    Call our San Antonio line or our Austin line and you get the same six steps. Estimates are free in both markets.

Roof Insurance Claim Help in San Antonio: What It Actually Means

You file the claim with your insurer. After that, a lot has to happen before the money shows up: somebody documents the storm damage, meets the adjuster at the house, goes through the carrier's scope line by line, files supplements for whatever got missed, does the work, and sends in the paperwork that releases the final payment. That's roof insurance claim help, and in San Antonio Texas-RRR does all six pieces in-house, with former adjusters on staff.

It matters more here than most places. Bexar County is hail country. On April 12, 2016, hail up to 4.5 inches fell in Helotes, and that storm became the costliest hail event in Texas history at the time, with about 1.36 billion dollars in insured losses. Then on April 28, 2021, a Texas-record 6.4 inch hailstone came down in Hondo while a second cell ran through San Antonio and Boerne, east along I-10 toward Seguin. In 2025 Texas led the country with 902 major hail events. Own a roof in San Antonio or Boerne? You'll file a hail claim sooner or later. What you can control is whether someone who knows the process is standing next to you.

Most claims get decided at the adjuster meeting. That adjuster might have a dozen roofs to get through that day. Creased shingles on the back slope, dented soft metals, cracked pipe boots: if nobody on your side points them out, they don't make the scope. We chalk and photograph every one before the adjuster pulls up, so the meeting starts from our evidence and not a quick glance at the front slope from the driveway. Storm work starts with a free inspection from our storm damage team. If it's hail, the claim side goes through our hail damage insurance claims service.
Our Six-Step Insurance Claim Process

We've run this same six-step process for years. Below it's written out step by step: who's doing what, what our part is, and about how long each stage takes. Carriers and storm volume both change the timing a lot. After something like the September 2023 Round Rock hail, carriers can take weeks just to assign adjusters. The short version? We give you a free estimate, meet your adjuster on the roof, audit the carrier's scope, file a supplement for what it missed, build the roof, and collect your recoverable depreciation once the final inspection's done. You file the claim and pay the deductible.

  1. Step 1: Free Estimate. Who acts: you and Texas-RRR. What we do: inspect the roof, decking, gutters, siding, fences and sheds, chalk and photograph every hit, and write up a damage report you can file with. If the damage isn't worth a claim, we'll say so. Typical timing: one visit.
  2. Step 2: Meet the Adjuster. Who acts: you file the claim, the carrier assigns an adjuster. What we do: show up for the adjuster's visit and walk the roof with them hit by hit, so the scope matches the real damage. Texas law requires the insurer to acknowledge your claim within 15 days of receiving it. Typical timing: one to three weeks after filing, longer after a regional storm.
  3. Step 3: The Audit Process. Who acts: Texas-RRR. What we do: our former adjusters hold the carrier's scope sheet up against our inspection and local code. The usual gaps are drip edge, starter strip, ice and water barrier, decking, ridge vent, or a second layer of tear-off. Typical timing: two or three days after the scope arrives.
  4. Step 4: Supplemental Report. Who acts: Texas-RRR and the carrier's desk adjuster. What we do: write the supplement with photos, measurements and code citations, send it in, and keep following up until the carrier approves the revised scope. Typical timing: one to four weeks depending on the carrier.
  5. Step 5: Begin Building. Who acts: Texas-RRR crews. What we do: once the carrier signs off on the scope we order materials, tear off, replace any bad decking, install the new roof system with Owens Corning or GAF products, and clean up. Most residential re-roofs finish in one to two days, and our roof replacement page covers what goes into the build. Typical timing: scheduled once the approved scope and your deductible are in hand.
  6. Step 6: Inspection and Recoverable Depreciation. Who acts: Texas-RRR and the carrier. What we do: a final walk-through with you, then we submit the completion certificate and final invoice that release the recoverable depreciation the carrier held back. Mortgage company on the check? We'll provide the lender's inspection paperwork too. Typical timing: carriers usually release depreciation within two to three weeks of receiving the invoice.

Six steps is a lot. We know. But homeowners who skip steps three and four almost always leave money on the table, money that was already theirs under a policy they've been paying for.

Recoverable Depreciation, Supplements and the Mortgage Endorsement

First claim in Texas? These three terms trip up almost everybody. Here's what each one means, and how it changes what the carrier ends up paying for your roof.

What is recoverable depreciation?

It's the chunk of your roof's replacement cost the insurer holds back until the work is done. Most Texas homeowner policies pay in two installments. Check one is the actual cash value (ACV), which is the full replacement cost minus depreciation for the roof's age, minus your deductible. Check two, the recoverable depreciation, comes after you prove the crew replaced the roof. Never finish the job, or never send the invoice, and the carrier keeps that second payment. It happens every storm season. That's why step six is in our process at all.

What is a supplement?

It's a documented request to add what the adjuster's first scope left out. A correction, really, more than a negotiation. On San Antonio roofs we commonly supplement for decking replacement found during tear-off, code-required drip edge and ice and water barrier, high-profile ridge cap, extra labor on steep or multi-story slopes, and the gutters, fences and siding the hail hit on its way down. Our former adjusters write supplements in the carrier's own estimating language. That's a big part of why they get approved instead of argued over. A desk reviewer at the carrier checks each added line against the same pricing database the adjuster used and either approves it or asks for proof. Good photos plus a code citation usually settle it the first time.

Why is my mortgage company on the check?

Your lender has a financial stake in the house. So if there's a mortgage, the carrier usually makes the claim check out to you and the mortgage company together, and you can't cash it until the lender endorses it. Most servicers have a loss-draft department. They'll either endorse the check and send it back, or hold the funds and release them in draws as the work passes inspection. We've been through this with hundreds of lenders. Our advice: call your servicer early and get the loss-draft requirements in writing. We'll supply our City of San Antonio contractor registration, W-9, lien waiver and completion certificate they want.

Why Deductible Waiving Is Illegal in Texas

We won't waive your deductible. We won't absorb it, rebate it or "take care of" it either, and no other roofer in Texas legally can. House Bill 2102 passed in 2019, took effect September 1 that year, and created Chapter 707 of the Texas Insurance Code. Under it, offering to pay a policyholder's deductible is a Class B misdemeanor, and insurers can demand proof you paid it before they release recoverable depreciation. So when a contractor offers to "eat" it, one of two things is going on. Either the invoice gets inflated to cover the difference, which is insurance fraud, or corners get cut on your roof to make the numbers work.

Look at it this way. Texas wind and hail deductibles commonly run 1 to 2 percent of the dwelling coverage amount. That's real money, and it's yours to pay. What a good contractor can do, legitimately, is make sure the carrier pays for everything the policy covers so the deductible is the only thing coming out of your pocket. Our audit and supplement steps exist for exactly that. You can see how it plays out in our reviews, where whole roofs got approved after a carrier first offered to patch a corner. If a roofer leads with a deductible pitch, that tells you plenty about how the rest of your claim would go.

What Homeowners Say About Our Claim Help

Four of our Google reviews talk about the insurance process. Here they are, word for word.

Yvette D.: "I contacted RRR roofing when a tree fell on my roof. Not only did they do an extremely professional and outstanding job fixing my roof, they dealt with the insurance company so I didn't have to. They're knowledge and experience helped me get the best settlement." She continues: "After RRR roofing inspected my roof with the claims adjuster, I was able to obtain what I needed to get my whole roof fixed with very little out of pocket. They had my roof upgraded and fully repaired in one day by very professional staff."

Cory L.: "We got a quote for a metal roof and they were rejected by our insurance." After our team got involved: "their team had us approved and repaired in less than 13 days. Our roof color is a much better match to our brick and wife is happy."

Elizabeth T.: "New Roof and siding and it was all covered by insurance. To my disbelief the roof of the house was in terrible condition. Now it's perfect."

Alma T.: "Our entire roof was replaced after the initial inspection of insurance adjuster and Texas-RRR. Materials were ordered promptly and once the work began, it was nonstop until the job was completed. The roof looks great!! I would highly recommend this company to anyone looking for this type of work. Thanks, Charlie!!"

See the pattern? One started with a lowball offer. One was a denied metal roof. One homeowner had no idea her roof was failing. Each claim turned once somebody who understood the carrier's process got involved, and honestly, that's the whole service. Cory's job shows the six steps moving fast: a denied metal quote to an approved, finished roof in under 13 days, with the adjuster meeting, audit, supplement and build all inside that window. And Yvette's one-day repair came after we walked her roof with the claims adjuster. That's the step most homeowners skip.

Claim Help Across the San Antonio and Austin Metros

We're based in San Antonio, and our crews work claims from Helotes to Seguin and up I-35 through New Braunfels. Up in the Austin area, homeowners get the same team by calling our Austin line. Their hail history isn't any kinder. On September 24, 2023, 4 inch hail hit Round Rock and did roughly 600 million dollars in damage across Travis and Williamson counties, and then the April 22, 2025 storm went through Georgetown and east Round Rock again. In Austin, Pflugerville, Cedar Park or Georgetown, the six steps work exactly the same.

A word about timing. Most Texas policies only give you a limited window after the storm date to file, often a year or two, and the longer you wait, the harder carriers push on proving when the damage happened. Storm came through last spring and nobody's looked at the roof? Get the free inspection now instead of waiting for a leak. We date-stamp every photo and match the damage pattern to storm reports for your address, which is the evidence a carrier wants on an older claim. Our hail damage roof repair page covers what we look for. To get on the schedule fast, use the contact page.

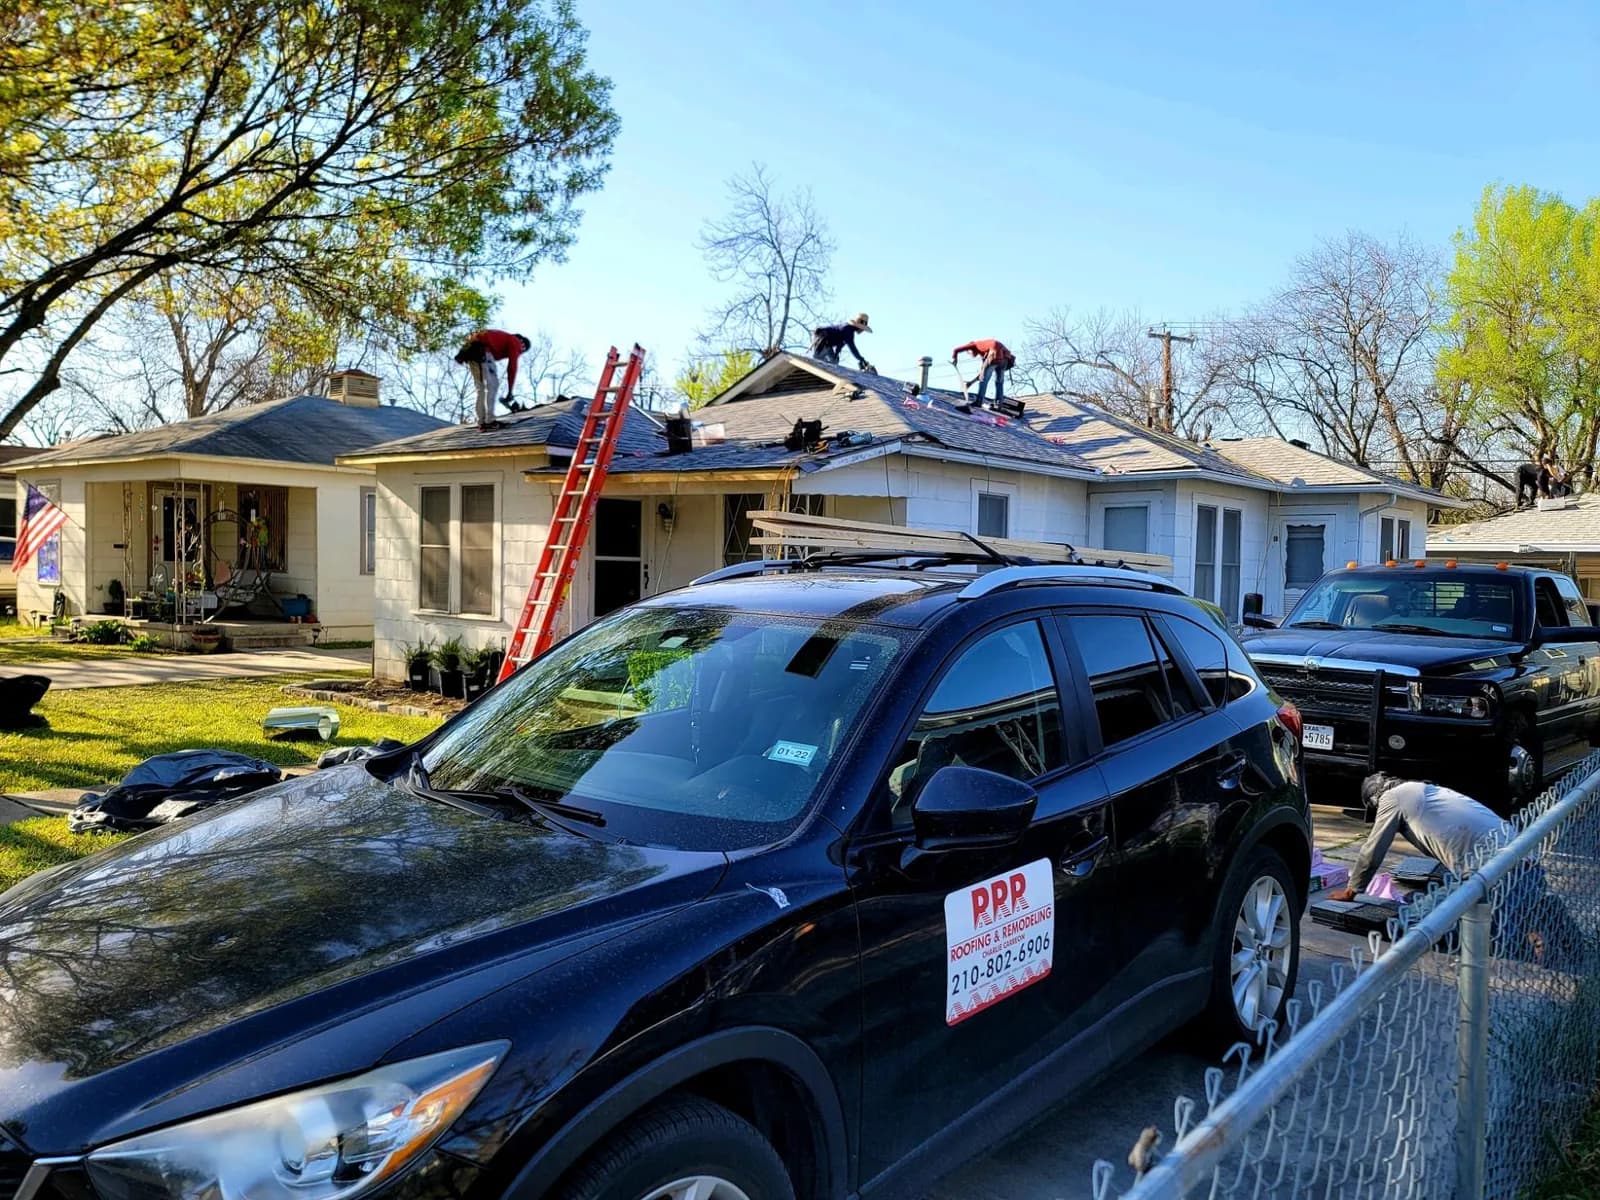
Roofing crews on two neighboring single-story homes with a company car and work truck parked out front.

Why Texas-RRR for Your Roof Claim

A lot of roofers learned insurance claims by losing a couple. We learned them from the inside. Texas-RRR's in-house staff includes former insurance adjusters, so whoever reads your carrier's scope sheet has written hundreds of them, and that's often the difference between a claim that pays for half a roof and one that pays for the whole thing.

We're veteran owned. We bring 30+ years of insurance claim experience, 8 full crew teams and 2,800+ completed projects across the San Antonio and Austin metros. Read our reviews and one name keeps coming up: Charlie Carreon, our owner. Owens Corning and GAF are our preferred roofing brands, and we're registered and insured. Claim customers have their say on our reviews page, and the full build sequence is on our process page.

Projects completed
2,800+
Full crew teams
8
Charlie's years in roofing
30
Google rating from 16 reviews
5.0

Insurance Claims questions, answered

Free estimates, Mon to Sat, 7 AM to 6 PM

Start Your Roof Claim With Former Adjusters on Your Side

Free inspection, a documented damage report, and people who'll meet your adjuster on the roof. Call (210) 802-6906 or ask for your free estimate online.

Call NowStart your insurance claim