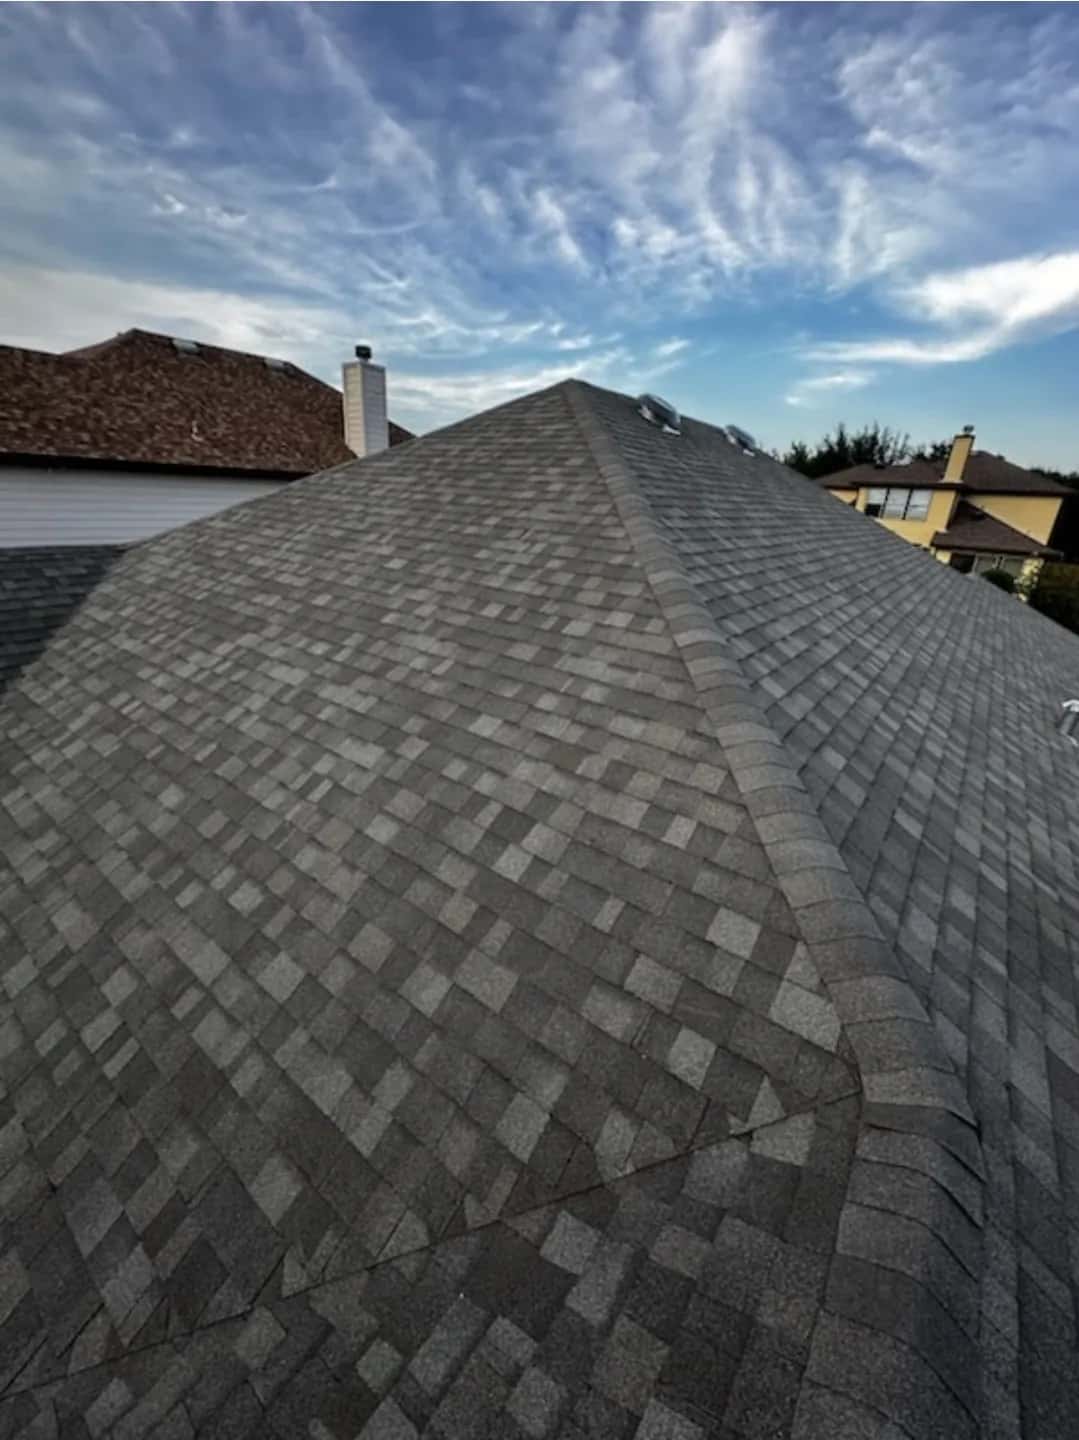
Gray architectural shingle hip roof with ridge caps and box vents under streaked clouds

Insurance Claims

Wind Damage Roof Insurance Claims in San Antonio and Austin

Hail leaves dents. Wind leaves arguments. Wind damage roof insurance claims in San Antonio and Austin, TX get denied for reasons a hail claim rarely runs into: the carrier says the shingles were old, nailed wrong or damaged some other day. Texas-RRR answers that with evidence. Our in-house staff includes former insurance adjusters, and the team brings 30+ years of insurance claim experience. We document the wind damage, connect it to the storm date and meet your adjuster on the roof. The inspection is free.

  • Storm date tied to the damage
  • Wear versus wind, documented
  • Repairability checked on site
  • Interior water traced to the opening

Preferred
brands

Owens CorningGAF

Google5.016 reviews

  • Veteran Owned
  • Registered and Insured
  • San Antonio and Austin

What is included with wind damage insurance claims

  • Storm date tied to the damage

    Your date of loss gets matched to the reported wind event, and we photograph damage that lines up with the direction the wind came from.
  • Wear versus wind, documented

    Creased tabs, torn nail lines and missing shingles on the windward slopes don't look like age. We show the adjuster why.
  • Repairability checked on site

    If your shingles crack when they're lifted, a spot repair might not be possible. We run that test with the adjuster watching.
  • Interior water traced to the opening

    Lots of policies cover rain damage inside only if wind opened the roof first. We photograph that opening before anybody patches it.
  • Austin line, same claim team

    Claims in Austin, Round Rock and Pflugerville go through the same former adjusters who handle our San Antonio claims.

Why Wind Claims Get Denied in Austin

A gust gets under a row of shingles, breaks the seal, folds them back and drops them flat again. Stand in the street afterward and the roof looks fine. That's the whole problem with a wind damage roof insurance claim, where you're asking the carrier to pay for shingles, ridge caps and flashing a storm tore, creased or blew away. Hail leaves marks that are hard to argue with. Wind doesn't.

So the same roof can come back on the adjuster's report as "wear and tear," "installation defect" or "no storm-related damage found." Every one of those can be argued. But the evidence has to be on the roof, in photos, before anybody repairs it.

On Austin wind claims, three denial reasons come up far more than the rest:

  • Age. The carrier says the shingles failed because they're old and brittle, not because of the storm.
  • Installation. High nailing, or too few nails, let the shingles lift, and some adjusters call that a defect the policy won't cover.
  • Timing. If the carrier can't match the damage to a storm on your date of loss, it treats it as older damage.

None of those is automatically wrong. Some roofs really have aged out, and if yours has, we'll tell you. Then again, a storm like the May 28, 2025 microburst, with a 77 mph gust measured at the Austin airport, tears up good roofs too. Proving which kind you've got is the job. If the roof itself still needs fixing, our wind damage roof repair crews take care of that side.
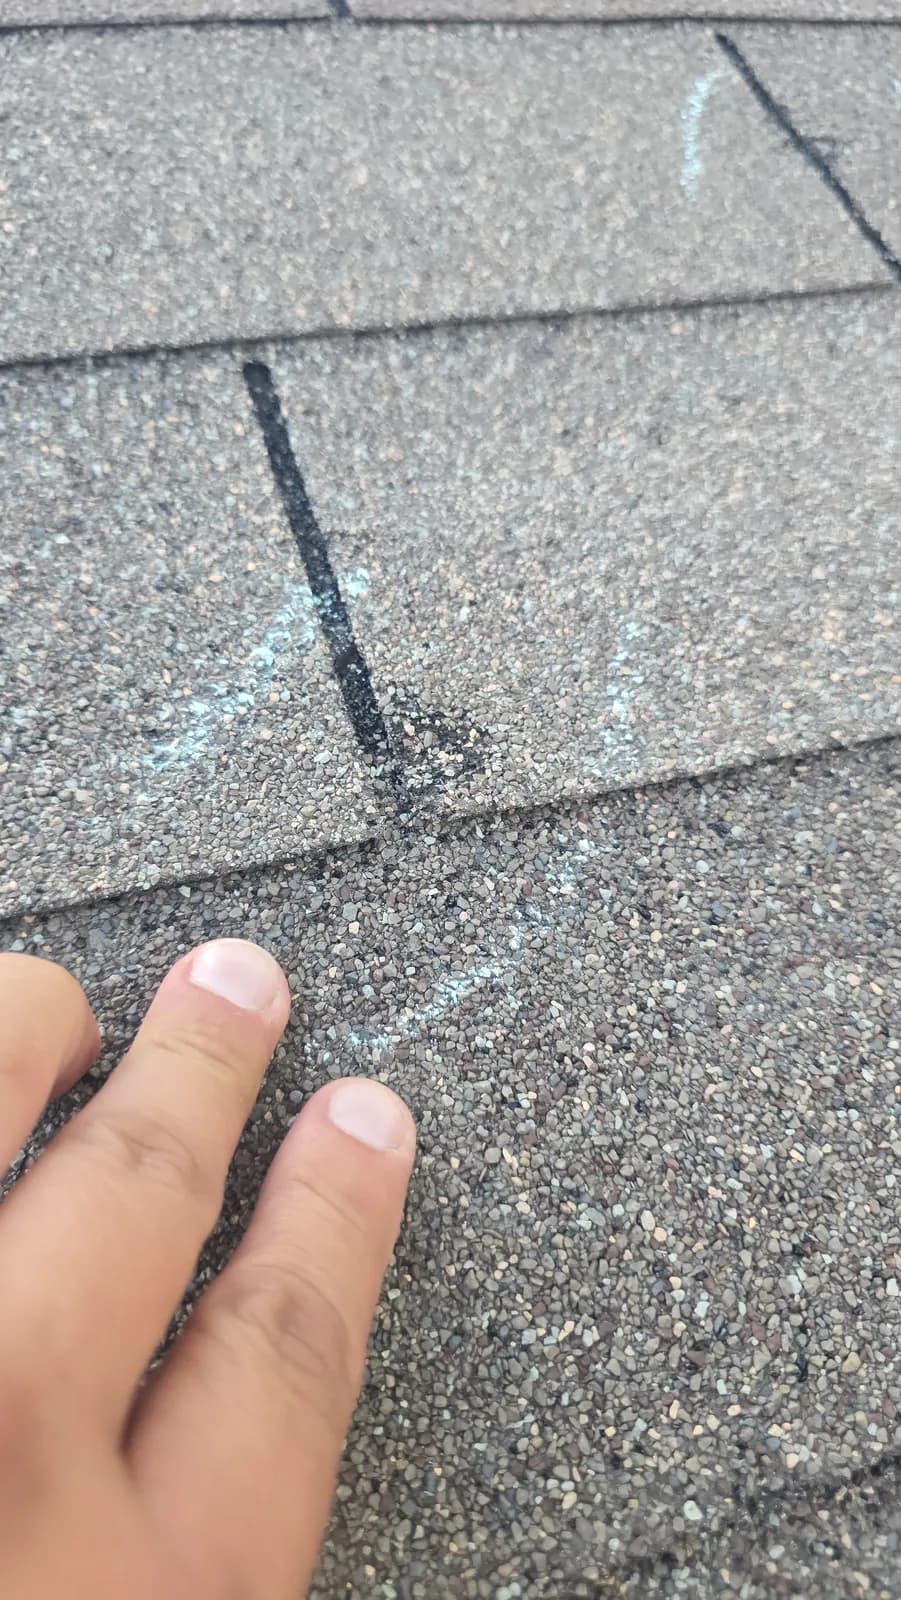
How We Document a Wind Damage Roof Insurance Claim

Since our in-house staff includes former insurance adjusters, we put the file together the way a carrier reads it. For wind, that comes down to four things.

The storm date. We match your date of loss to the wind event reported for your area. Name the right storm, with its date and reported gusts, and it's a lot harder for anyone to wave the damage off as old. Direction. The slopes facing the gust take the worst of it, so we photograph and count creased, torn and missing shingles slope by slope. A clear pattern on the windward side makes the case better than any argument could.

Repairability. Older shingles tend to crack when you lift them to slide a new one in. If they crack during the test, patching may not be possible, and the scope needs to say so. We'd much rather run that test while the adjuster's standing there.

The opening. Many homeowner policies pay for rain damage inside the house only if wind opened the roof or a wall first. Got a stained ceiling? We photograph the opening that let the water in before anybody tarps it, and that one photo can decide whether the policy pays for your drywall. If water's coming in right now, call our emergency roof repair crew first. We'll document while we tarp.

After that, we meet your adjuster on the roof and walk the damage together.

Texas Rules That Shape a Wind Claim

A few of the rules that matter most come from state law, not your carrier, and knowing them makes your claim harder to stall.

Claim deadlines. Chapter 542 of the Texas Insurance Code, the prompt payment law, sets the clock. Once you give notice, the insurer generally has 15 days to acknowledge the claim and start investigating. After it has the items it asked for, it generally has 15 business days to accept or deny, then 5 business days to pay once it accepts. The Texas Department of Insurance explains these deadlines, and the extensions allowed, on its website. Keep a log of every date: when you reported the claim, when the adjuster came out, when each document went in. If a deadline slips, that log is what you show your carrier or TDI.

Your deductible. Most Austin homeowner policies have a separate wind and hail deductible, and Chapter 707 of the Insurance Code bars any contractor from waiving it or paying it for you.

Who negotiates. Texas Insurance Code chapter 4102 licenses public adjusters and bars a contractor from acting as one on a property it's repairing. We don't negotiate your settlement, and nobody here will pretend otherwise. It's your claim. Our part is documenting the damage, meeting the adjuster, writing the repair scope and sending supplements with photos when the first estimate leaves out work the storm caused.

Your carrier, not TWIA. The Texas Windstorm Insurance Association only writes coverage along the coast. Homes in Travis and Williamson County file wind claims with their own homeowner carrier.

From the First Photo to the Final Check

Every claim we work goes through the same six steps listed on our insurance claims page, starting with the free estimate and ending with the recoverable depreciation release. Hail has its own quirks, covered on our hail damage insurance claims page, and when a storm brings both, we document them together.

Texas-RRR is veteran owned, registered and insured, with 8 full crew teams and 2,800+ completed projects. Our Austin line covers Austin, Round Rock, Pflugerville and the rest of Travis and Williamson counties. From Yvette D.'s Google review: "After RRR roofing inspected my roof with the claims adjuster, I was able to obtain what I needed to get my whole roof fixed with very little out of pocket."

Send us your address for a free inspection. Real wind damage, we'll show you. Plain wear, we'll tell you that too.

Wind Damage Insurance Claims questions, answered

Free estimates, Mon to Sat, 7 AM to 6 PM

Get a Free Wind Damage Inspection Before You File

Call (210) 802-6906 or send your address. We'll inspect the roof, record the damage by slope and storm date, and be there when your adjuster comes out.

Call NowFree estimate